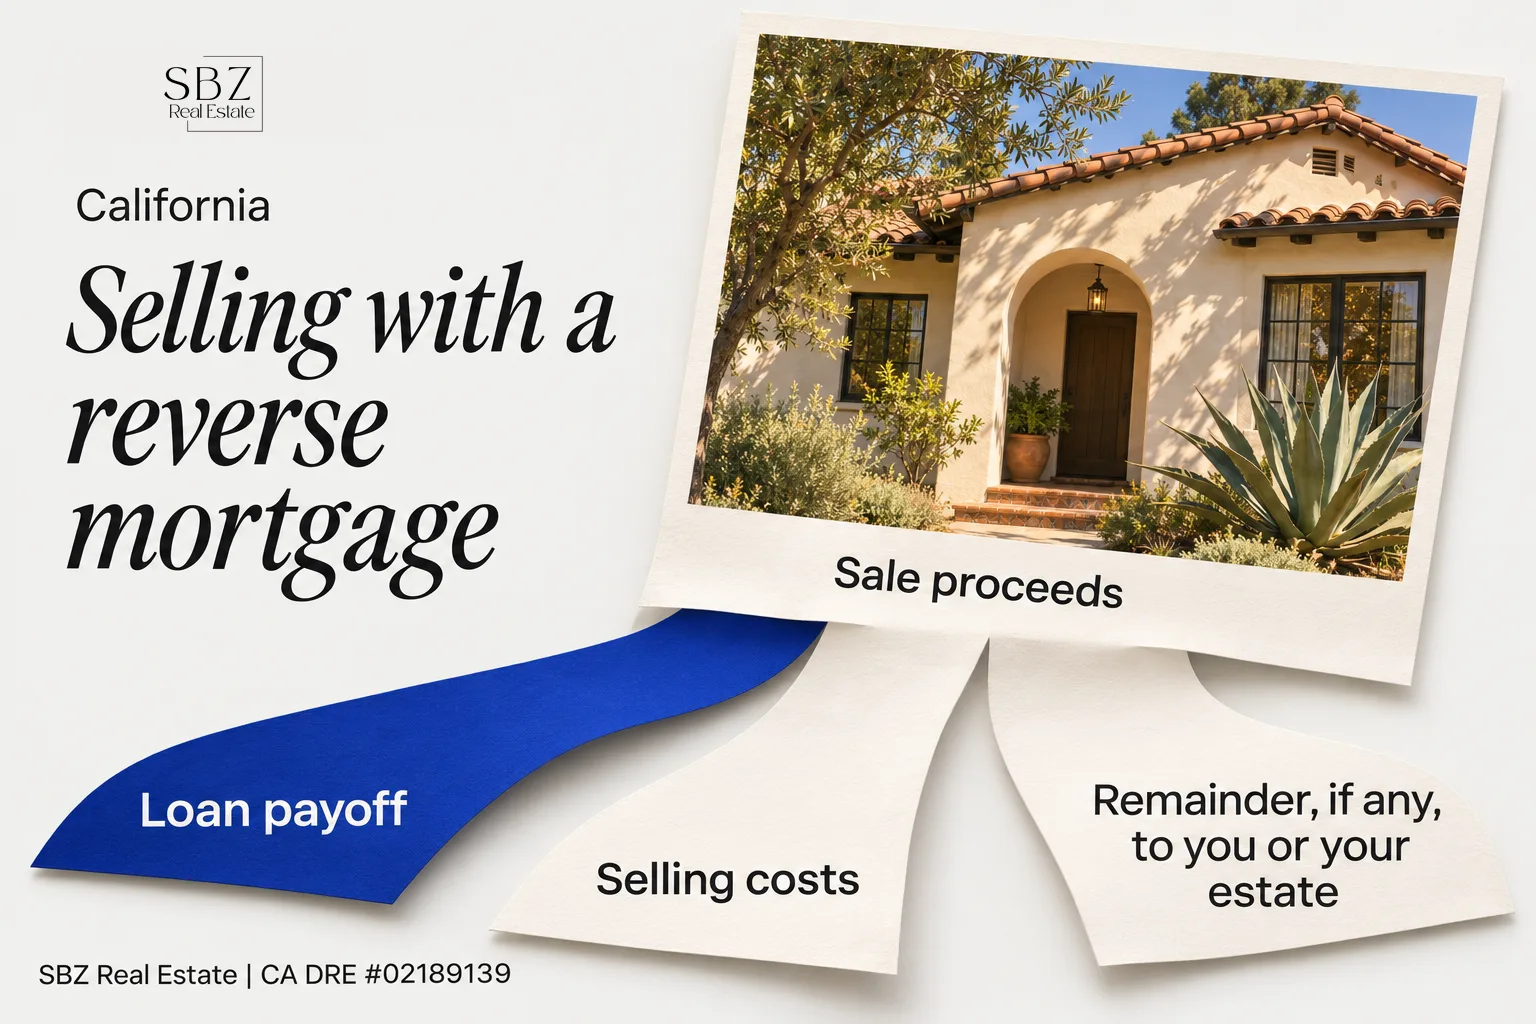
Yes, you can sell a house with a reverse mortgage. The loan balance is paid off from the sale proceeds at closing, and anything left over goes to you, or to your estate if the borrower has passed away.
For most owners, the sale itself looks a lot like any other. The difference is a payoff step and a few rules about timing and who can act. Here is how it works in practice, and where the process tends to get stressful.
What happens to a reverse mortgage when you sell?
A reverse mortgage is a loan secured by your home, and it must be repaid when the home is sold. Most are federally insured Home Equity Conversion Mortgages (HECMs), and the loan becomes due when the last borrower sells, moves out permanently, or passes away.
At closing, escrow pays the reverse mortgage servicer the full payoff amount. That includes the principal you borrowed, accrued interest, and mortgage insurance premiums and servicing fees if your loan has them. The remaining proceeds are paid to the seller after the other normal closing costs. How escrow works in California is worth a read if you haven't been through a sale recently.
How do you find out what you owe?
Contact your loan servicer and request a written payoff statement. Don't rely on the balance in your last statement, because interest keeps accruing every month. The payoff figure is good only through a specific date, and escrow will request an updated one as closing approaches.
Ask for the statement before you list. Knowing the payoff up front tells you whether the sale will leave you with meaningful equity or only enough to clear the loan. A seller net sheet puts that payoff next to your other costs so you can see the real result before you commit.
Will you walk away with anything?
It depends on the home's value against the loan balance, and I won't guess without your numbers. A reverse mortgage balance grows over time because interest and fees are added to it. The longer the loan has been in place, the less equity there may be.
Selling costs come out of the same proceeds, including agent commission, title and escrow charges, and transfer taxes. Our guide on the cost of selling a house in California breaks those line items down. Market prices and your loan's history both matter here, so treat any rule of thumb with caution.
What if the home is worth less than the loan?
Most HECMs are non-recourse loans. That means you or your heirs generally will not owe more than the home is worth, even if the balance is higher. The insurance on the loan covers the lender's shortfall. Check the terms of your own loan with your servicer or a HUD-approved housing counselor, because older or non-HECM reverse mortgages can differ.
If the balance is close to or above the value, price and timing matter more than usual. A realistic pricing strategy for Los Angeles-area homes helps avoid sitting on the market while interest keeps accruing.
Can you sell if the borrower has passed away?
Yes. Heirs or the estate can sell, but the loan becomes due and the servicer will send a notice. Under HUD's HECM rules, heirs generally get an initial window to sell or pay off the loan, and extensions are available in some situations if they are actively working on a sale. Confirm the exact dates in the servicer's letter and keep the servicer informed in writing.
Heirs who want to keep the home can typically repay the lesser of the full balance or a percentage of the appraised value, per HUD guidelines. Anyone in this position should ask the servicer for the current terms.
Authority to sell matters too. If the home passed through probate or a trust, the executor or trustee signs the listing and sale documents. Our article on inheriting a house in California under Prop 19 covers the property tax side, and capital gains on inherited property explains the stepped-up basis.
What about a spouse who isn't on the loan?
This is the situation I see cause the most heartache. If a spouse is not a borrower on the reverse mortgage, their right to stay in the home after the borrower passes depends on the loan's rules for eligible non-borrowing spouses and on whether certain conditions were met. If you're in this position, speak with the servicer and a housing counselor before anything else, and ask an attorney about the title.
What does the selling process look like?
The steps are familiar, with one extra layer of coordination.
- Request the payoff statement from your servicer.
- Get a market analysis so you know a realistic price range.
- Prepare the home. Our list of what to fix before listing helps you spend only where it pays off.
- Complete required disclosures. California requires them regardless of your loan type. See seller disclosures in California.
- List, negotiate, and open escrow. Escrow orders updated payoff figures from the servicer.
- Close. The servicer is paid first from proceeds, and you receive the balance.
If you sell while living in the home, you will need to move out by closing. A reverse mortgage requires the home to remain your primary residence, so build your move into the timeline early. A rent-back after closing is something to negotiate with the buyer, not assume.
What about taxes?
Reverse mortgage loan advances are generally not treated as income. Selling may still create a capital gain, depending on your original purchase price and improvements. Our overview of capital gains on selling a house in California explains the home-sale exclusion. Confirm your own situation with a CPA.
Who should you talk to before listing?
Three people are worth a call: your loan servicer for the payoff, a HUD-approved housing counselor if you have questions about the loan itself, and a broker who has handled sales with an existing lien. A full-service sale should include the payoff coordination as part of the work, not as an add-on.
If you're weighing a move, a quick conversation costs nothing. You can reach us here and we'll walk through your numbers with no pressure.
Related reading
Frequently asked questions
Can I sell my house if I have a reverse mortgage?
Yes. The reverse mortgage is paid off from the sale proceeds at closing, and you keep the remaining equity, if any. You need a written payoff statement from your servicer to know the exact amount.
Do I have to pay off the reverse mortgage before I list?
No. You don't need cash on hand. Escrow pays the lender from the sale proceeds at closing, so the payoff happens as part of the transaction.
What happens if I owe more than the house sells for?
With most HECMs, you or your heirs generally will not owe more than the home's value, because the loan is non-recourse. Verify the terms of your specific loan with your servicer or a HUD-approved counselor.
Can my heirs sell a home with a reverse mortgage after I pass away?
Yes. Heirs or the estate can sell, but the loan becomes due and the servicer sets deadlines. Heirs should contact the servicer promptly and ask about the time allowed.
Does a reverse mortgage make the sale take longer?
It adds a coordination step, since escrow must obtain and update payoff figures from the servicer. The main delays come from slow payoff requests or title questions, so starting early helps.