Affordable homes for sale in Southern California do exist, but they are rarely found by sorting a search portal by lowest price. The homes that are truly affordable are the ones where the purchase price, the monthly payment, and the ongoing costs all fit your budget together.
This guide covers the Southern California market. Searches for affordable housing often return results for other states, and the rules here are different. Here is how I help buyers think it through.
What does "affordable" actually mean when buying a home?
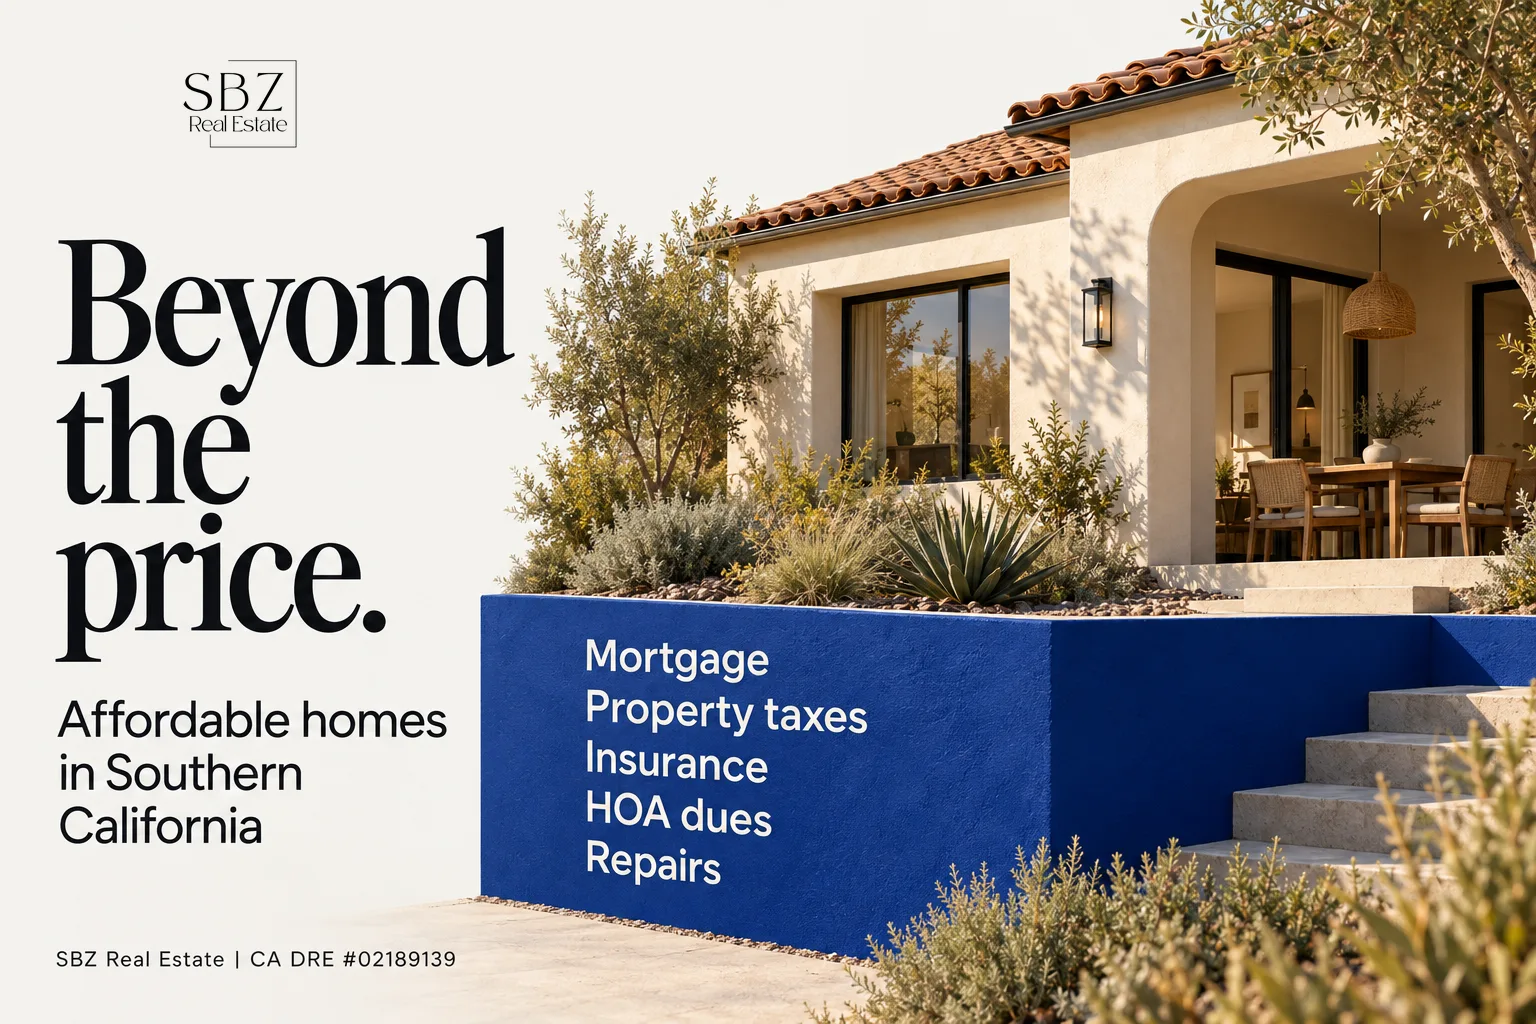
Affordable means the total monthly cost of owning the home is comfortable for your income. That cost includes the mortgage payment, property taxes, insurance, any HOA dues, and any special assessments. A lower price can still produce a heavy monthly bill if the home carries extra costs.
It also helps to separate two meanings of the word. In the general market, "affordable" simply means lower-priced relative to the surrounding region. In housing policy, "affordable housing" usually means income-restricted or deed-restricted homes offered through government or nonprofit programs, with eligibility rules attached. Most buyers searching "affordable homes for low income" are really asking about the second kind, and the answers are different.
Where are the more affordable parts of Southern California?
Generally, the farther you get from the coast and the central job centers, the more purchase price you get for your money. That is a long-standing pattern in this region, though specific prices shift constantly. Check current listings and recent sales rather than trusting any number you read in an article, including this one.
For many buyers, the Antelope Valley is where that tradeoff shows up most clearly. Palmdale and Lancaster offer a range of single-family homes, and the commute and climate are the tradeoffs worth weighing honestly. If you're comparing the two, our guide to Palmdale vs. Lancaster walks through the practical differences. Santa Clarita and parts of the San Fernando Valley sit at different price points and offer different commutes.
The point is not that one area is "the" answer. It is that your budget, your commute, and the type of home you need all interact. A condo or townhome in a closer-in area can sometimes compete on monthly cost with a larger house farther out.
What costs sit on top of the purchase price?
The price is the headline, but these line items decide whether a home is truly affordable:
- Property taxes and special assessments. Some newer neighborhoods carry additional bond-based assessments. Our explainer on Mello-Roos taxes in the Antelope Valley shows how to spot them before you fall in love with a house.
- HOA dues. Common in condos, townhomes, and some newer developments. They count toward your monthly obligation when a lender evaluates you.
- Insurance. Homeowners coverage varies by property age, location, and risk factors. Get a quote before you write an offer.
- Closing costs. These are paid at the close of escrow and add up. See closing costs for home buyers in the Antelope Valley for the categories to expect.
- Repairs. Lower-priced homes are often older, and deferred maintenance is where an "affordable" home can quietly become expensive. Read what home inspections reveal in older Antelope Valley homes before you assume a bargain.
How much do you need for a down payment?
Less than many buyers assume, though it depends on the loan type. Conventional loans, FHA loans, and VA loans for eligible veterans each have different minimums and different mortgage insurance rules. A larger down payment lowers your monthly payment, but draining your savings completely is its own risk.
We cover the tradeoffs in how much to put down on a house. The short version is that the right number leaves you with a reserve for repairs and emergencies after closing.
Are there programs that help with affordability?
Yes. Several options exist for California buyers, and eligibility depends on income, location, purchase price, and whether you are a first-time buyer. Examples include down payment and closing-cost assistance offered through the California Housing Finance Agency (CalHFA), plus local city and county programs and mortgage credit certificate programs that can reduce your federal tax liability.
Program terms, funding, and income limits change often, and some programs run out of funds. Confirm current details directly with the program administrator and a licensed lender before you build a plan around any of them. Our first-time home buyer guide for California and the Antelope Valley is a good starting point, and if your credit needs work, see buying in Lancaster with bad credit.
Can distressed or foreclosed homes be a path to a lower price?
Sometimes, but they are not the shortcut they appear to be. Bank-owned and distressed properties can come with condition issues, tight timelines, and competition from investors paying cash. Any discount has to be weighed against repair costs and risk. Foreclosed homes in Los Angeles explains how buyers actually find and buy them, and what to watch for.
How should you start your search?
Start with the monthly payment you're comfortable with, not the highest price a lender will approve. Get pre-approved so you know your real range, then work backward to a target price. From there, compare communities, home types, and total ownership costs side by side.
A good broker helps by pulling real comparable sales, flagging hidden costs early, and telling you when a "deal" isn't one. You can see how we approach it on our buying a home page.
If you're weighing a move and want a straight read on what your budget can realistically buy, a quick conversation costs nothing. You can reach out here whenever you're ready.
Frequently asked questions
What is considered an affordable home in Southern California?
There's no single price. A home is affordable when the full monthly cost, including taxes, insurance, and any HOA dues, fits comfortably within your income. Prices vary widely by city and property type, so check current local sales data.
Are affordable homes for low-income buyers different from regular listings?
Often, yes. Income-restricted or deed-restricted homes are offered through government or nonprofit programs and come with eligibility requirements and sometimes resale limits. Regular listings have no income test, but down payment assistance programs may apply to them.
Is a cheaper home always the better deal?
No. A lower price can come with higher repair needs, HOA dues, or special assessments that raise your monthly cost. Compare the total cost of ownership, not just the price.
Can I buy an affordable home with a small down payment?
Many buyers do, using loan programs designed for lower down payments. The tradeoff is usually mortgage insurance and a higher monthly payment, so talk through the numbers with a licensed lender.
Do I need an agent to find affordable homes?
You aren't required to use one, but an experienced broker can help you compare real comparable sales, spot hidden costs, and negotiate. Their guidance is especially useful when your budget leaves little room for surprises.